Tax moves
Gains in an ISA or a SIPP are free of capital gains tax; gains in a GIA are not. A tax move shifts holdings from a GIA into a sheltered account a little each tax year, using the CGT allowance so the move itself costs no tax. You place the trades yourself at your broker. Gains are estimates from average cost, not figures for your tax return.
Bed & ISA
Each April, sell some of a fund in a GIA, pay the proceeds into an ISA and buy the same fund there. The household holds the same funds; the ISA holds more of them.
How much: up to the GIA owner's CGT allowance left (the gain divided by the fund's gain per £1 on its average cost), or a fixed £ you set. It is also capped by the ISA allowance left and by what the GIA holds; the panel says which cap applies. The payment into the ISA counts against its allowance, so the plan's saving goes elsewhere that tax year once it is full.
Asset location swap
Each April, swap a growth fund in a GIA with a steadier fund in a SIPP or ISA: four equal legs on one day, so the household holds the same funds and the model is still met, but the growth fund's future gains are sheltered.
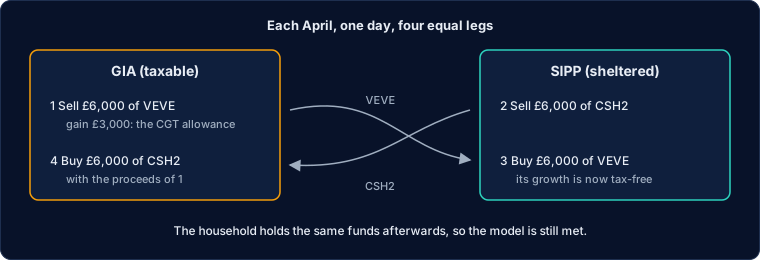
You choose both funds; the plan does not pick them. The size is set as for Bed & ISA, and the swap stops when either side runs out. Choose a fund with a gain on the GIA side: one below cost would realise a loss and put the growth on the wrong side.
When they run
Once a tax year, at the first daily check from 6 April (within three weeks). Bed & ISA runs before any swap, so a swap gets the allowance Bed & ISA leaves. The plan does not rebalance on the same day.
Backtests and the projection paths worked out trade by trade run them each April from their own simulated gains. The quick projection leaves them out: it does not model tax yet, and a tax move changes nothing else.
Last updated 2026-10-27.